Classification conclusion
HS 2022 created heading 8485 for additive-manufacturing machines; this guide classifies plastic-deposition FDM printers.
| Field | Conclusion |
|---|---|
| Proposed HTS code | 8485200000 — Machines for additive manufacturing by plastics or rubber deposit |
| Jurisdiction | United States |
| Tariff edition | HTSUS 2026 |
| Rules applied | GIR/GRI 1 and 6 |
| Confidence | High when the entered merchandise matches the stated facts |
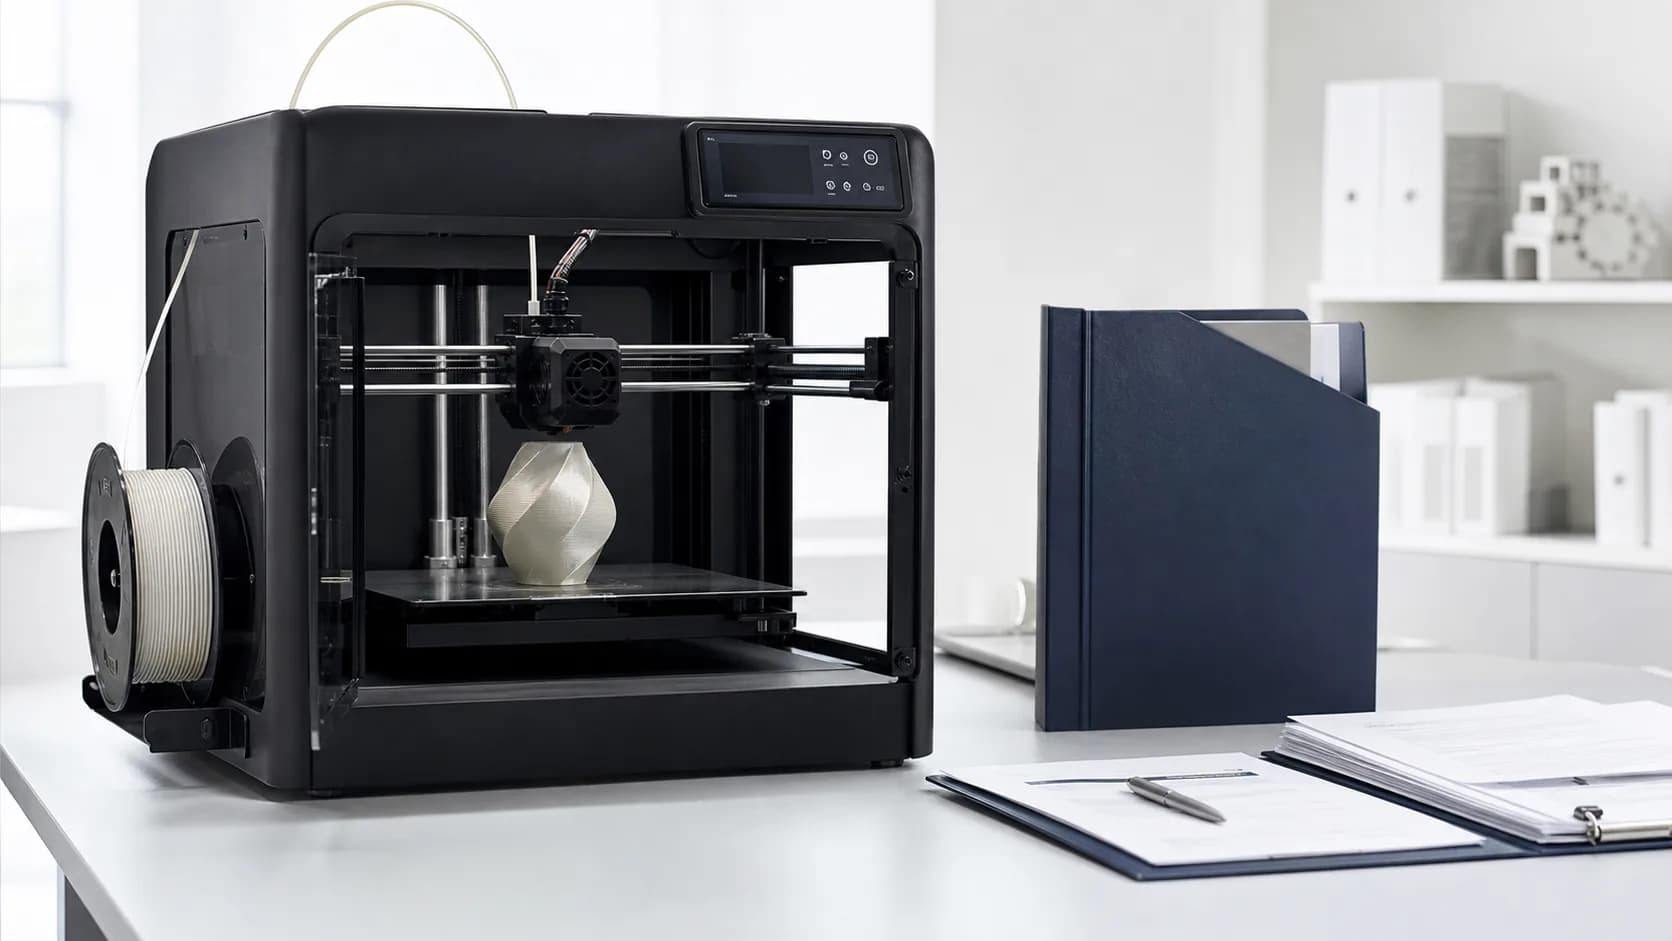
| Condition | A complete fused-deposition-modelling machine that builds three-dimensional objects layer by layer from thermoplastic filament such as PLA, ABS or PETG. |
Classification conclusion and tariff codes
HS 2022 created heading 8485 for additive-manufacturing machines; this guide classifies plastic-deposition FDM printers.
- US: 8485200000 — Machines for additive manufacturing by plastics or rubber deposit
Goods covered by this analysis
A complete fused-deposition-modelling machine that builds three-dimensional objects layer by layer from thermoplastic filament such as PLA, ABS or PETG.
Classification basis and reasoning
- GIR 1 applies heading 8485, introduced in HS 2022 to name machines for additive manufacturing directly.
- GIR 6 selects 8485.20 because the deposited material is plastics or rubber; the machine's trade name 'printer' does not move it to office-printer heading 8443.
When a new classification is required
- Metal-deposition machines use 8485.10; plaster, cement, ceramic or glass deposition uses 8485.30.
- Parts are classified separately under 8485.90 and must not be reported as complete additive-manufacturing machines.
Evidence to retain for customs entry
- Deposition technology
- Feedstock material
- Complete machine or part
Official legal sources and relevant rulings
- US — United States International Trade Commission; HTSUS 2026: Harmonized Tariff Schedule of the United States
- US — United States International Trade Commission; HTSUS heading 8485: Machines for additive manufacturing
Limits of this conclusion
The US HTS reporting number above applies only when the imported merchandise matches the facts stated in this article. Before entry, verify the current HTSUS, applicable Chapter 99 provisions and trade-remedy measures; a material change in construction, function or condition as imported requires a new classification analysis.
2026 U.S. customs and import-law review
Legal review date: September 5, 2026. The USITC online HTSUS identified 2026 Revision 18 on this review date. Rates and Chapter 99 measures can change during the year, so the legally operative schedule is the edition in effect on the entry date.
1. Quick legal conclusion
The proposed reporting number is 8485200000 for Machines for additive manufacturing by plastics or rubber deposit, but only for merchandise that matches this defined scope: A complete fused-deposition-modelling machine that builds three-dimensional objects layer by layer from thermoplastic filament such as PLA, ABS or PETG. This is a fact-dependent classification opinion, not a CBP ruling and not a determination of admissibility, origin or AD/CVD scope.
2. Facts that must be verified before entry
- Deposition technology
- Feedstock material
- Complete machine or part
Also obtain the complete bill of materials, technical drawings, model numbers, operating manual, condition and configuration as imported, transaction chain, manufacturer/producer, country of origin of material inputs and intended U.S. use. A material difference requires a new analysis.
3. HTSUS analysis and controlling authority
- GIR 1 applies heading 8485, introduced in HS 2022 to name machines for additive manufacturing directly.
- GIR 6 selects 8485.20 because the deposited material is plastics or rubber; the machine's trade name 'printer' does not move it to office-printer heading 8443.
The analysis must begin with GRI 1, the heading text and binding Section/Chapter Notes, then proceed to GRI 2–5 only if legally necessary and to GRI 6 for subheadings. U.S. Additional Rules of Interpretation and Additional U.S. Notes are controlling where applicable. WCO Explanatory Notes are persuasive interpretive material but are not U.S. statutory text. A CROSS ruling is binding only for the requester and merchandise covered by its facts; materially similar rulings may be persuasive. CIT and Federal Circuit decisions control within their jurisdiction.
Goods outside this opinion include:
- Metal-deposition machines use 8485.10; plaster, cement, ceramic or glass deposition uses 8485.30.
- Parts are classified separately under 8485.90 and must not be reported as complete additive-manufacturing machines.
For recurring or high-value entries, request a prospective binding ruling from CBP under 19 CFR Part 177 and disclose all material facts. A ruling request is not a substitute for checking post-ruling HTSUS amendments or trade remedies.
4. Duty, fee and tax matrix
| Charge | Legal treatment for this article |
|---|---|
| HTSUS Column 1 General duty | Apply the rate printed beside 8485200000 in the HTSUS edition effective on the entry date. Any rate stated elsewhere in the article remains provisional until that check is completed. |
| Merchandise Processing Fee (MPF) | Formal entries generally incur 0.3464% of entered value, excluding duty, freight and insurance, subject for FY 2026 to the CBP minimum $33.58 and maximum $651.50; an applicable preference program can alter MPF treatment. |
| Harbor Maintenance Fee (HMF) | 0.125% of value when commercial cargo is unloaded from a vessel at a covered U.S. port; it ordinarily does not apply to air freight. See 26 U.S.C. 4461–4462 and 19 CFR 24.24. |
| Section 301 / other Chapter 99 duty | Determine from the exact 8-digit HTSUS provision, country of origin, effective date and any valid exclusion. Report the required Chapter 99 number; do not assume the base HTS rate is the total landed duty. |
| Section 232 | Check current Chapter 99 notes, product/derivative coverage, origin and any required steel/aluminum/copper content, melt-and-pour or smelt-and-cast data. It does not apply merely because the article contains some metal. |
| AD duty | Not determinable from an HTS number. The written scope of an AD order is dispositive; HTS references are for convenience. Review product, producer/exporter, origin and circumvention findings. Cash-deposit and final assessment rates can differ. |
| CVD duty | The same written-scope rule applies. Confirm the case-specific company or all-others cash-deposit rate and liquidation instructions in Commerce ACCESS and ACE. |
| Safeguard / quota | Check current Chapter 99, quota and safeguard measures as of entry. Product scope, origin, quantity and quota period control. |
| Federal excise tax | No product-specific federal excise tax is identified from the stated facts; confirm the intended use and the current Internal Revenue Code before entry. |
| State sales/use and other state taxes | These are not CBP customs duties. They depend on destination, importer nexus, later sale/use and state/local law and require a separate domestic-tax review. |
This table does not calculate landed cost. The importer must also determine customs value under 19 U.S.C. 1401a, including assists, packing, royalties/license fees, proceeds and related-party acceptability. A “first sale” claim requires a bona fide sale for export to the United States, arm's-length evidence and a complete transaction trail.
5. AD/CVD and evasion review
Do not infer trade-remedy status from the HTS number alone. Screen the country of origin, producer and written scope of every active AD/CVD order, and test any applicable Chapter 99 provision as of the entry date.
The written scope description is dispositive; an HTSUS number in an order is only a convenience reference. If coverage is uncertain, obtain a Commerce scope ruling under 19 CFR 351.225 before relying on a non-covered position. Minor processing or assembly in a third country can trigger a circumvention analysis. False origin, undervaluation or evasion can lead to EAPA investigation under 19 U.S.C. 1517 and civil penalties under 19 U.S.C. 1592.
6. Partner Government Agency and product compliance
FCC Part 15 may apply to digital or wireless functions. Imported resins, powders, filaments or other chemical preparations must be separately reviewed for TSCA certification and workplace hazard communication; the printer's HTS classification does not resolve the materials' status.
PGA admissibility is independent of tariff classification. Transmit all required agency data and documents through ACE; a CBP release does not cure a violation of an FDA, CPSC, EPA, FCC, DOT, USDA or other agency rule.
7. Origin, marking and UFLPA
Determine nonpreferential origin under the substantial-transformation test and any product-specific rule; do not rely only on the shipping country, invoice origin or location of final packing. Mark the article and, when required, its container under 19 U.S.C. 1304 and 19 CFR Part 134, unless a documented exception applies. Section 301, AD/CVD, government procurement and a preference program may use distinct origin rules.
Under 19 U.S.C. 1307 and the UFLPA, goods mined, produced or manufactured wholly or in part in Xinjiang, or by an entity on the UFLPA Entity List, are subject to a rebuttable presumption of exclusion. Maintain supplier identity, production, payment, logistics and input-tracing evidence; a generic supplier declaration is not enough for a high-risk supply chain.
8. Minimum entry file
- CBP entry/cargo release data and Form 7501 record, customs bond, commercial invoice, packing list and bill of lading/air waybill.
- Purchase orders, payment records, Incoterms, assists/royalties analysis and related-party or first-sale valuation support.
- Product specifications, drawings, photographs, manuals, composition/BOM, model cross-reference and condition as imported.
- Signed classification memorandum applying the GRIs, legal notes, current HTSUS text and relevant rulings, plus rejected alternatives.
- Origin and marking analysis; producer/supplier affidavits and traceability records; Chapter 99 and exclusion support.
- AD/CVD scope search, producer/exporter case numbers and cash-deposit instructions, even when the conclusion is “not covered.”
- All PGA registrations, certificates, laboratory reports, licenses, notices and ACE data required for this product.
Keep entry and supporting records for the statutory period, generally five years, under 19 U.S.C. 1508 and 19 CFR Part 163.
9. Principal legal risks
- Declaring a 10-digit number from the trade name without proving the imported condition and legally relevant characteristics.
- Omitting a Chapter 99 number or calculating only the Column 1 rate.
- Treating an AD/CVD HTS cross-reference as dispositive instead of reading the written scope.
- Using shipping country as origin without a substantial-transformation and marking analysis.
- Filing before PGA admissibility, certificates, laboratory evidence or supply-chain traceability are complete.
An incorrect entry can produce redelivery, exclusion/seizure, duty reassessment, interest, loss of liquidation defenses and penalties. If past entries contain a material error, promptly evaluate a post-summary correction, protest, prior disclosure under 19 CFR 162.74 or other corrective procedure with U.S. customs counsel; the correct route depends on entry and liquidation status.
10. Pre-entry action checklist
1. Lock the specifications and imported configuration for the exact SKU. 2. Re-run classification against the current HTSUS and record GRI/Note reasoning. 3. Determine customs value, nonpreferential origin and marking. 4. Screen Chapter 99, Section 301/232, quota/safeguard and every potentially relevant AD/CVD scope. 5. Complete the product-specific PGA review and obtain supporting certificates before shipment. 6. Calculate landed duties and fees, then have the importer and licensed customs broker validate ACE reporting. 7. For unresolved or commercially material classification issues, obtain a CBP Part 177 ruling before importation.
Official legal sources
- United States International Trade Commission; HTSUS 2026: Harmonized Tariff Schedule of the United States
- United States International Trade Commission; HTSUS heading 8485: Machines for additive manufacturing
- USITC — Current Harmonized Tariff Schedule of the United States
- CBP — User fee table: MPF rate and FY 2026 minimum/maximum
- CBP — Harbor Maintenance Fee
- CBP — ACE: filing customs and Partner Government Agency data
- USTR — Section 301 tariff actions and exclusion search
- BIS — Section 232 steel and aluminum measures
- Commerce — AD/CVD FAQs, scope and circumvention rules
- Commerce — ACCESS AD/CVD proceeding search
- CBP — UFLPA rebuttable presumption
- CPSC — Certificates and mandatory eFiling guidance
- FDA — Importing food products into the United States
- EPA — TSCA requirements for importing chemicals
- PHMSA — Lithium battery transportation requirements
- FCC — Equipment authorization
- eCFR — 19 CFR Part 177: administrative rulings
- eCFR — 19 CFR Part 134: country-of-origin marking
- eCFR — 19 CFR Part 163: recordkeeping
> Legal notice: This article provides general U.S. customs and trade-compliance information based on the stated facts as of September 5, 2026. It is not a CBP, Commerce or PGA ruling and is not legal advice for a specific transaction. Current HTSUS/Chapter 99 text, agency requirements and case-specific AD/CVD instructions must be rechecked at entry.
Editorial note
Prepared by the Global HS Code Checker Editorial Team for customs-classification, tariff and import-policy research. The correct code and applicable measures may change with the merchandise's actual characteristics, jurisdiction, entry date and supporting record. Verify the current tariff, governing measures and competent customs authority before filing an entry. A reviewer is identified only after a named expert has completed the review.